Entreprises
Cross River and Offchain bring tokenization into loan origination
The two companies completed a proof of concept on Arbitrum One and are targeting production deployment in early 2027, without changing the bank’s regulatory role.
 Ryan MitchellEditorial pen name
Tokenization enters the origination process
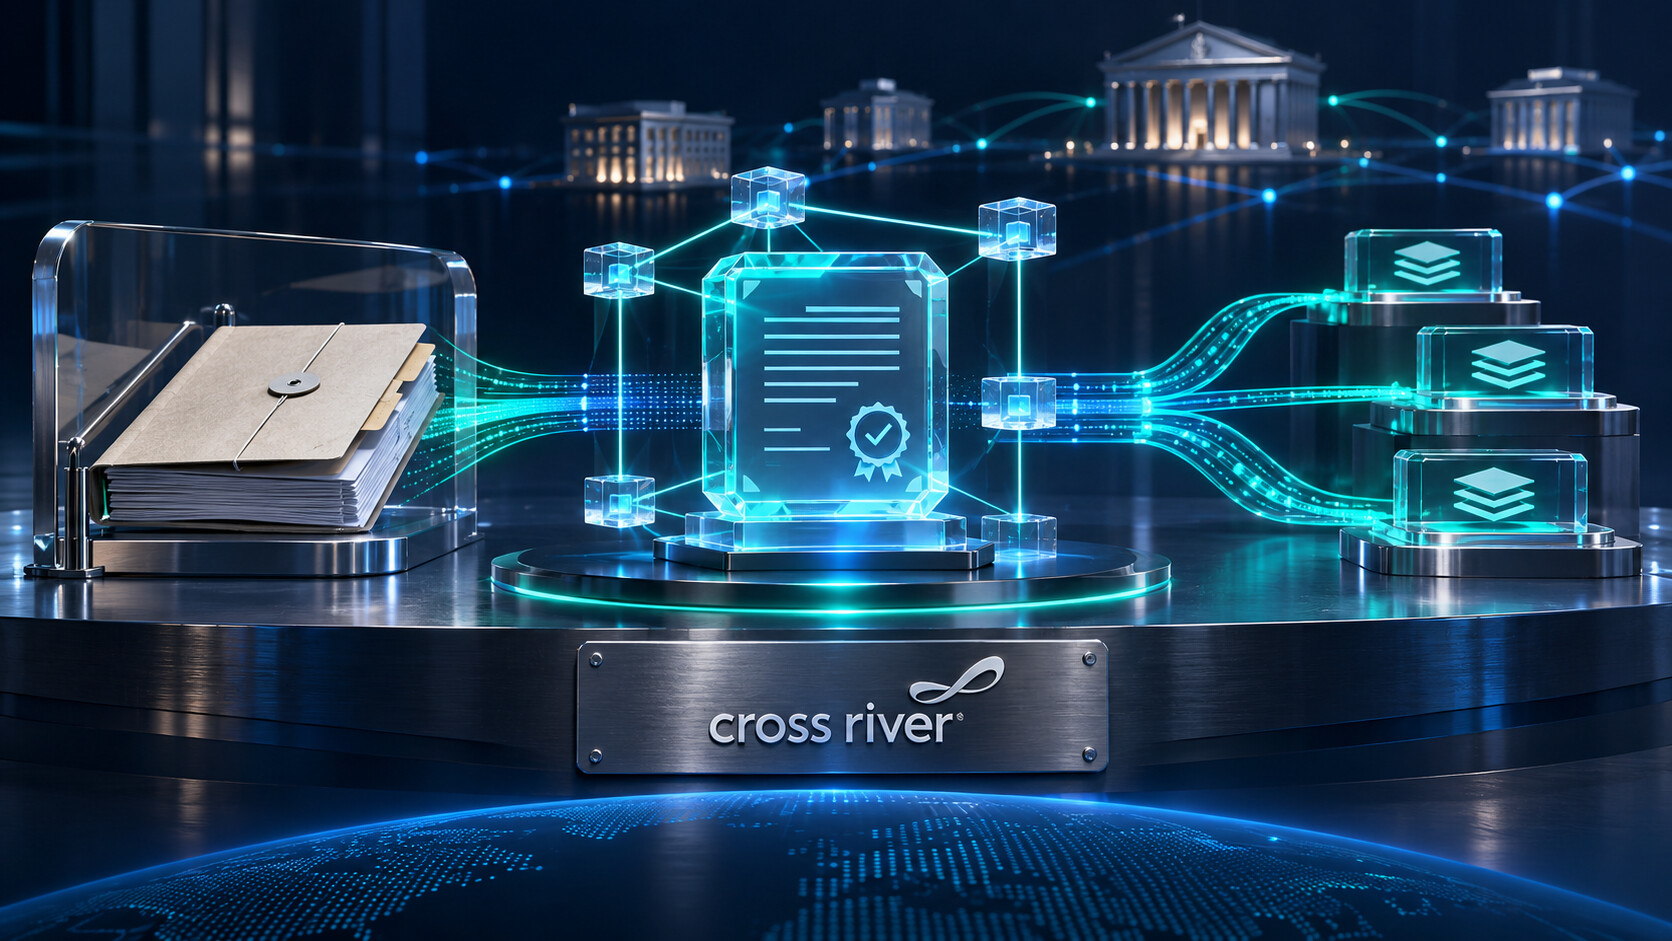
Cross River and Offchain announced on November 3, 2026 a partnership to integrate tokenization directly into Cross River’s lending platform. Their approach is designed to make a loan fundable, ownable, transferable and serviceable on Arbitrum One from the moment it is created. That differs from projects that move an already originated and distributed asset from traditional systems onto a blockchain. The partners say they have completed a proof of concept and are now working toward a production deployment targeted for early 2027.
The proposal does not replace the borrower-facing journey. Applications, funding and repayments are expected to continue through the familiar interfaces used by Cross River’s partners. In the background, ZeroDev wallet infrastructure supplied by Offchain is intended to place ownership, funding, payments and servicing activity on a shared record. The announcement describes an architecture under development, not a service already applied to every loan or a guarantee that it will be available on a fixed date.
One shared record across the asset lifecycle
The model aims to reduce breaks between loan origination, ownership and distribution. An asset could be funded onchain from day one and later transferred among investors without rebuilding its history across several disconnected systems. Cross River highlights continuous forward-flow purchase programs, more flexible commitment sizes and new methods for packaging credit portfolios. Those uses will still depend on the final product design, agreements among participants and the rules that apply to the underlying assets.
Offchain is contributing its enterprise engineering services, Arbitrum One and ZeroDev smart-account infrastructure. Its teams are working alongside Cross River to adapt the product to the lending platform’s requirements. The release provides no expected asset volume, first-customer list or pricing. It also does not specify the exact mechanics of secondary liquidity. Those omissions matter: the proof of concept validates a technical direction, but it does not yet demonstrate broad commercial adoption.
The bank keeps its responsibilities
Cross River says it will remain the regulated bank and lender of record for assets originated through its platform. Tokenization is therefore not intended to change underwriting standards, risk controls or compliance obligations. It primarily changes how an asset may be funded, owned and distributed after origination. That separation between the regulated layer and the blockchain infrastructure is the central feature of the project presented by the two partners.
The stated timeline remains conditional. Following the proof of concept, the teams are building a production version targeted for early 2027. Before then, they must turn the architecture into an operating service, define controls, integrate partners and test end-to-end flows. The November 3 announcement therefore documents a specific development step in credit tokenization; it does not establish that Cross River loans are already being issued at scale on Arbitrum One.